PayOffPath
Closed Testing • Coming SoonAndroid
Organize your debts, compare payoff strategies, and see how extra payments can change your debt-free timeline.
When you need ₹1 Lakh to ₹3 Lakhs urgently for medical bills, family weddings, or home repairs, Indian banks offer multiple instant options. Here is the honest comparison of which one costs the least.
Moving high-interest credit card debt to a 0% introductory card sounds like free money. But with balance transfer fees rising to 3% or 5%, here is how to calculate whether you really come out ahead.
With online banks offering 4.5% to 5.0% on savings accounts, many people wonder: should I hoard cash in a high-yield account, or aggressively pay off my loans? Here is the honest math.
Most people don't realize that in the first few years of a mortgage or auto loan, up to 70% of each payment goes directly to bank interest. Here is how adding a little extra changes everything.
When you buy a flat in Bengaluru, Mumbai, or Pune, taking a 20-year home loan feels normal. But did you know you might pay more in interest than the flat itself? Here is how small part-payments change everything.
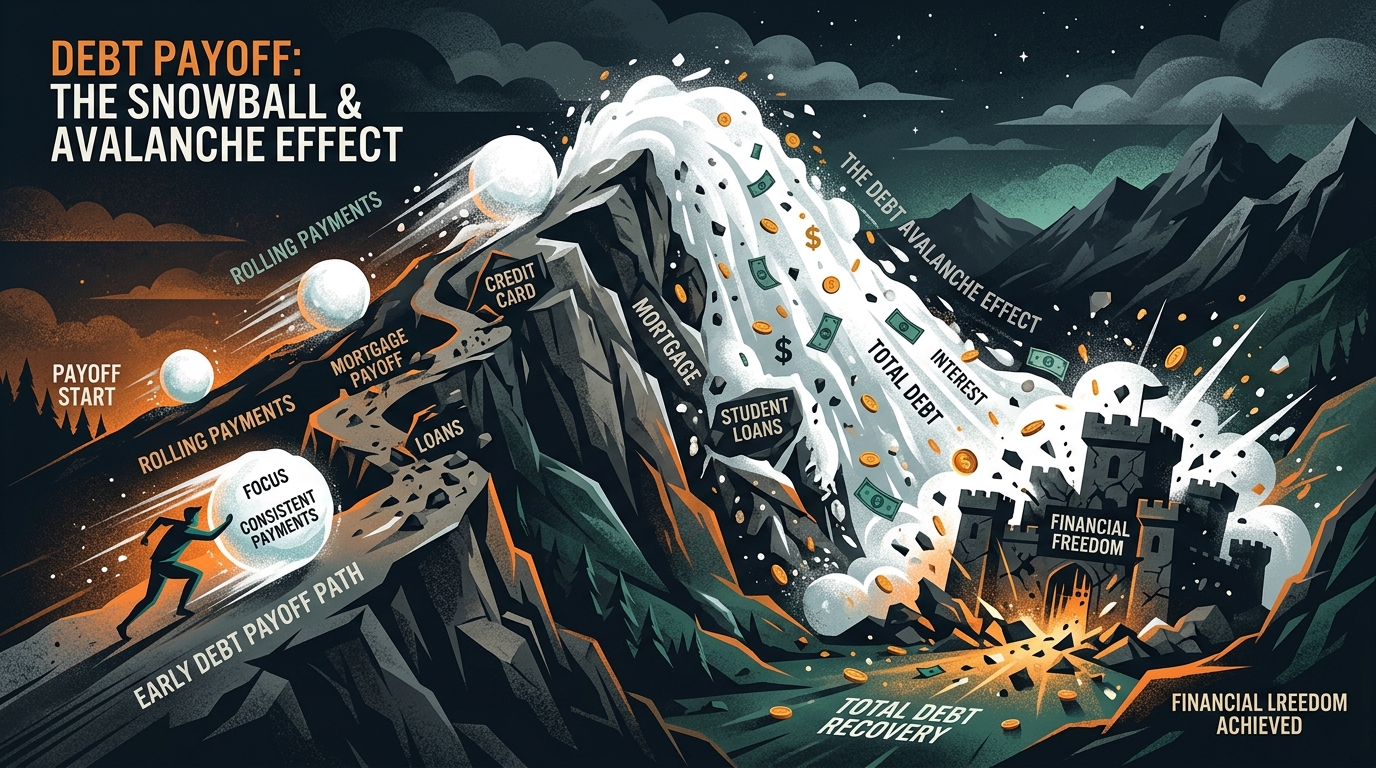
If you have multiple loans or credit cards, where should your extra cash go first? Here is the honest math, the mental side of debt, and how to pick the right strategy for yourself.
From sudden corporate layoffs to hospital emergencies not fully covered by insurance, an emergency fund is your financial shield. Here is how to calculate your number and where to keep it safely.
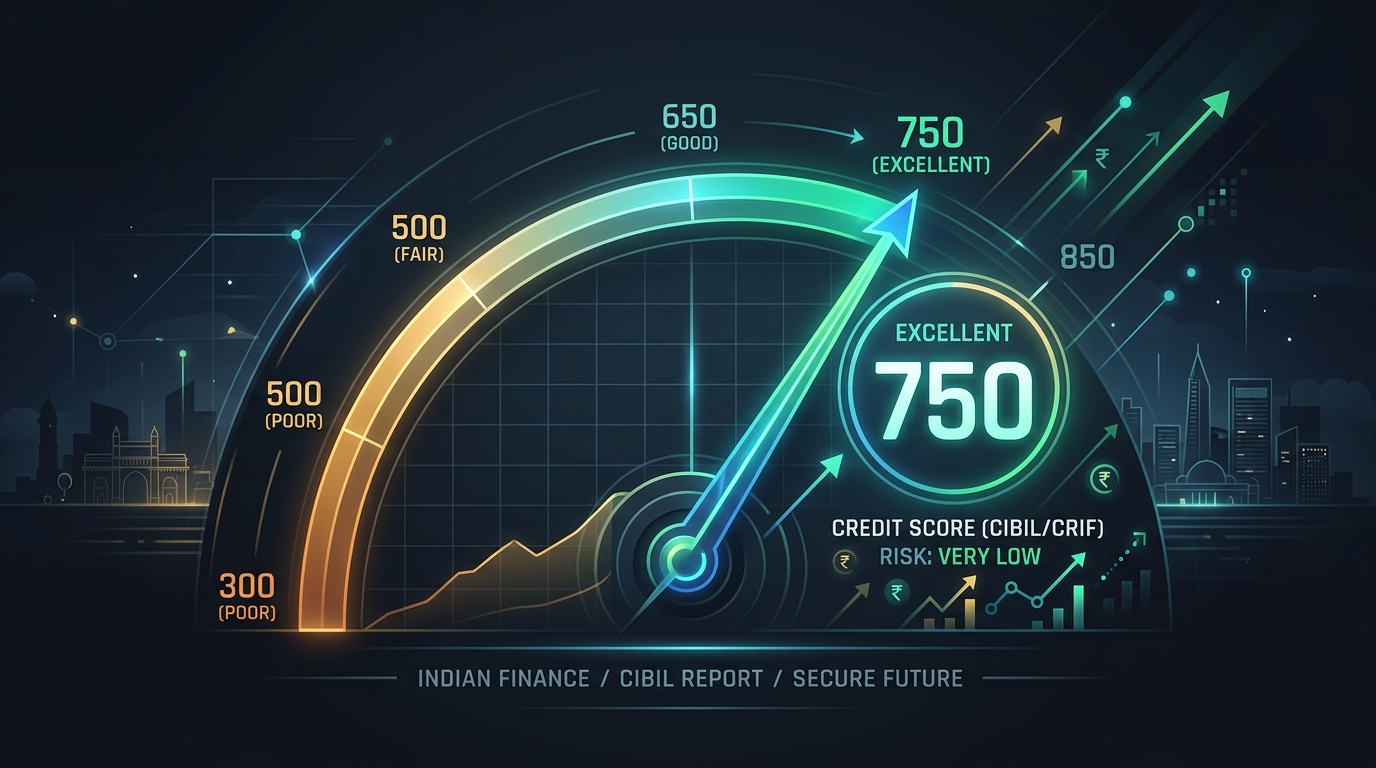
If you applied for a personal loan or home loan and got rejected because your CIBIL score was sitting around 650, don't panic. Here is the realistic roadmap to fixing it within 6 to 9 months.
When your monthly credit card statement arrives with a Total Due of ₹80,000, paying the ₹4,000 "Minimum Due" feels convenient. But here is the brutal truth of what banks don't highlight.
Do you pay your credit card in full every month, but your credit score still drops? You might be paying on the wrong day. Here is the simple timing trick that fixes it.
Organize your debts, compare payoff strategies, and see how extra payments can change your debt-free timeline.